

Autopilot - Investment App
by Autopilot Holdings Corporation
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
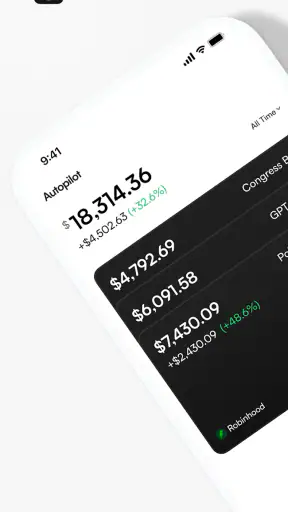
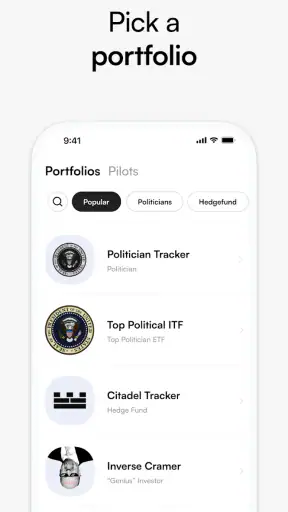
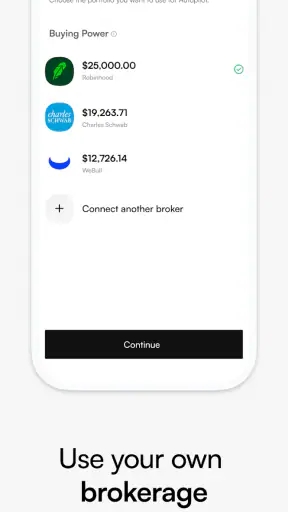
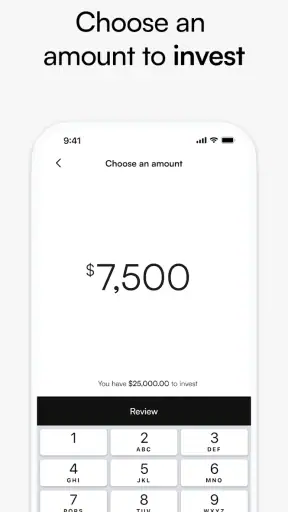
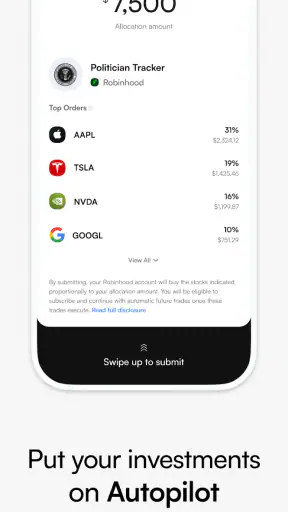
 Analysis by Getfullapps
I approached Autopilot as a finance app for people who want investing to feel more organized and less intimidating. Its central appeal is simple: instead of treating every investment decision as a separate research project, it gives you a more modern way to think about building and managing an investing routine. That makes it interesting for someone who is ready to move beyond leaving money idle, but does not want to spend every evening comparing financial products.
My first impression is that the app is best understood as a tool for structure rather than a substitute for financial judgment. It can help make investing feel more approachable, yet the responsibility for choosing an appropriate strategy still belongs to you. That distinction matters. A polished interface can reduce friction, but it cannot remove market risk, turn an unsuitable investment into a suitable one, or guarantee a particular result.
Autopilot is free to download and is listed for everyone, which lowers the barrier to trying it. It comes from Autopilot Holdings Corporation and has attracted more than a million installs, alongside a 4.7 average from around 7,400 ratings. Those figures suggest that the concept has reached well beyond a small group of finance enthusiasts, although popularity alone should not decide whether it fits your habits.
Getting a dependable investing routine started
The most useful way to begin is to treat the app as part of a repeatable process. I would not open it with the vague intention of “making money” and then react to whatever looks interesting. I would first decide what the money is for, how long it can remain invested, and how much uncertainty I can tolerate without abandoning the plan. Only then would I use the app to organize the next step.
This baseline workflow is especially helpful for a new investor. Start with a small, clearly defined amount that does not compete with rent, emergency savings, or near-term bills. Review the choices available in the app with a written purpose in mind, rather than selecting something simply because it is currently popular. After making a decision, record why you made it. That note becomes valuable later, when a market drop makes every earlier choice feel questionable.
I also recommend separating “checking” from “acting.” Looking at an account can become a nervous habit, particularly when prices move quickly. A better routine is to choose a review moment and use it to ask whether your original plan has changed. If the goal, time horizon, and ability to accept losses are still the same, a temporary price movement may not require a new action.
That does not mean ignoring the account. It means giving every review a job. One session might be for checking whether contributions are still affordable. Another might be for examining whether the investment mix still reflects your priorities. This approach keeps Autopilot from becoming a button you press whenever the market gives you an emotional reaction.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Who benefits most from this approach
I see the strongest fit among people who want a guided investing experience without building a complicated spreadsheet from scratch. A first-time investor can use the app as a central place to develop better habits, while a more experienced user may appreciate having a cleaner routine for monitoring decisions that have already been made.
It can also suit someone whose main problem is inconsistency. Many people understand the basic idea of investing but postpone it because every choice feels permanent. A focused app can make the first step feel more manageable. The important trick is to define a process before opening the app, so the convenience supports discipline instead of encouraging impulsive activity.
On the other hand, I would be cautious if you want detailed professional research, complex trading tools, or a full financial-planning service in one place. Autopilot’s modern presentation may be appealing, but a streamlined experience is not automatically the best environment for advanced analysis. If you need tax planning, retirement modeling, specialist advice, or highly specific order controls, a traditional brokerage or a qualified adviser may be a better companion.
Settings and choices worth checking early
Before settling into regular use, I would carefully review every available account, notification, and investment preference. The exact choices you see can depend on the device and account context, so I would not assume that an option exists merely because another finance app offers it. The practical lesson is to read each screen instead of tapping through setup on autopilot.
Notifications deserve particular attention. Helpful reminders can keep a contribution or review habit alive, but too many market alerts can turn long-term investing into a stream of distractions. I prefer notifications that support a planned action and silence anything that mainly encourages frequent price watching. If an alert makes you want to change a long-term decision immediately, it is probably not helping your process.
Privacy and security checks are equally important. Use a strong, unique password where applicable, protect the phone itself, and avoid signing in on shared devices. Finance apps deserve the same care as banking apps, even when the interface feels casual. I would also make sure I understand which account I am using before confirming an action, especially if the app is installed on a phone shared with family members.
Another useful setting habit is to review the app after an update rather than assuming that familiar screens work exactly as before. The current version is 1.19.23, and keeping software current is sensible, but updates can also alter navigation or the location of controls. A quick check of preferences after updating is less frustrating than discovering a changed setting only when you need it.
The app requires at least Android 10, so compatibility should be checked before planning your workflow around it. If your phone runs an older system, upgrading the device or using a different investing route may be more practical than forcing an unsuitable setup. For iPhone users, I would still review the current device requirements in the relevant store before installing, since operating-system support can vary by platform.
Faster patterns that remain responsible
Experienced use is less about moving quickly and more about removing repeated hesitation. I would create a short personal checklist and use it every time: confirm the account, confirm the amount, confirm the purpose, and pause before the final action. This takes little effort, but it prevents the most avoidable mistake in a finance app: acting on the wrong screen or with the wrong amount.
A second useful pattern is to separate research from execution. When an idea occurs to you, write it down or investigate it during a dedicated review period. Do not let a sudden thought turn directly into a transaction. By giving ideas a waiting period, you can tell the difference between a considered change and a reaction to a headline or a dramatic market session.
For recurring investing, consistency matters more than trying to identify the perfect moment. If your budget supports regular contributions, decide on a sustainable rhythm and treat it like another household commitment. The amount should be comfortable enough to continue during ordinary months, not so ambitious that one unexpected expense forces you to stop.
I would also keep a simple external record of decisions. It does not need to be elaborate. The date, amount, reason, and intended time horizon are enough to create useful context. This record protects you from rewriting history. When an investment performs well, you may remember the decision as obvious; when it performs poorly, you may assume it was foolish. A note made at the time gives you a more honest reference.
One non-obvious advantage of this habit is that it shows whether you are changing the plan too often. If your notes contain frequent reversals with no change in your goals or finances, the issue may not be the app or the investment. It may be that you are checking too often. In that case, reducing review frequency can improve the quality of your decisions more than adding another source of information.
Where the streamlined experience reaches its limits
Autopilot cannot make risk disappear. Investments can lose value, and an attractive user experience should never be confused with a promise of safety. I would be particularly careful if you need the money soon, have no emergency reserve, or would be forced to sell after a modest decline. In those situations, the right answer may be to improve cash reserves first rather than begin investing immediately.
There is also a difference between convenience and control. A modern app may be easier to navigate than a conventional brokerage, but experienced investors sometimes need granular tools, broader research, detailed reporting, or more control over order decisions. If those requirements are central to your strategy, Autopilot may work better as an accessible starting point than as your only financial platform.
Another limitation is psychological. Automation-themed branding can tempt users to believe that once the setup is complete, no further thinking is needed. I would resist that interpretation. A repeatable system still needs occasional review when your income, goals, family responsibilities, or tolerance for losses changes. The app can help you follow a plan, but it cannot know when your personal circumstances have changed unless you reassess them.
Fees and account terms should also be read carefully wherever they appear during the sign-up or transaction process. “Free” describes the app’s price, not a universal guarantee that every financial activity connected with investing has no cost. Before confirming anything, I would review the relevant terms and understand how money moves in and out of the account. That small pause is worthwhile in any finance product.
For users who want direct human guidance, the app may feel too self-directed. A financial adviser can ask questions about your broader situation and help connect investing with insurance, debt, taxes, and long-term planning. Autopilot is more appropriate when you are comfortable taking responsibility for those decisions or already have advice elsewhere.
How it compares with familiar alternatives
Compared with a conventional brokerage, Autopilot appears aimed at reducing the intimidation that comes with a crowded screen full of charts, order types, and research panels. That can be a real benefit for a beginner who would otherwise delay starting. The trade-off is that a simpler path may provide less of the detailed control that an active or highly analytical investor expects.
Compared with a bank’s basic investing option, the app’s identity feels more focused on making investing a deliberate routine rather than an extra menu item attached to everyday banking. That focus can help users take the process seriously. A bank may still be preferable if keeping cash, payments, savings, and investments under one established relationship is more important to you.
Compared with a do-it-yourself spreadsheet and a standard account, Autopilot can reduce the amount of manual organization required. The spreadsheet route remains attractive for people who want complete visibility and enjoy building their own tracking system. I would choose that approach for detailed household planning, but I would choose a dedicated app when the main obstacle is getting from intention to consistent action.
Compared with a professional adviser, the difference is not simply convenience. It is scope. An app can offer a structured self-service experience, while an adviser can interpret personal circumstances and help with decisions that extend beyond an investment account. If your finances are complicated or a mistake would be costly, professional advice may justify its additional effort.
What the audience and maturity suggest
The app is free and carries an Everyone content rating, which makes its entry point broad. That should not be read as a recommendation for every age or financial situation; investing still requires adult judgment, suitable funds, and an understanding of possible losses. Parents or guardians introducing a young person to the concept should focus on education and risk awareness rather than treating the app as a shortcut to wealth.
Its 4.7 average and roughly 1.1 thousand written reviews indicate a generally positive reception, while the release date of November 15, 2023, places it among relatively modern finance tools rather than a decades-old brokerage interface. I would take that combination as a reason to explore it, not as proof that it will match every investor. Reviews can reveal whether the experience feels comfortable, but they cannot decide whether the underlying approach suits your objectives.
In everyday use, imagine receiving income at the start of the month and wanting to invest a manageable portion after covering essentials. I would open the app during a calm planning session, confirm that the amount will not interfere with upcoming expenses, review the selected approach, and complete the action only after checking the account details. Later, I would review the result at a planned interval rather than repeatedly throughout the day. That workflow is intentionally uneventful, and that is its strength.
My verdict after building a repeatable habit
I like Autopilot most when it is used as a behavioral tool: a way to turn vague interest in investing into a routine with clear boundaries. Its free entry point, modern finance focus, and accessible presentation make it worth considering for beginners and for experienced users who want less clutter around a straightforward process.
The strongest result comes from combining the app with a written plan, restrained notifications, careful confirmation, and scheduled reviews. Those habits do more for decision quality than constantly searching for a faster button or a more exciting investment idea. They also expose the app’s proper role: it can organize your actions, but it cannot replace judgment.
I would skip it if you need advanced brokerage controls, detailed professional planning, or a person to guide every decision. I would also wait if your finances are too tight to tolerate investment losses. For everyone else, especially someone who keeps postponing investing because the usual alternatives feel complicated, Autopilot is a sensible app to test. Just use its simplicity as a reason to become more disciplined, not as an excuse to stop thinking.
Pros
- Automates recurring investments to help maintain consistent saving habits.
- Simple interface makes portfolio tracking easy for beginners.
- Supports goal-based investing for clearer financial planning.
- Useful performance charts help monitor portfolio progress over time.
- Can reduce emotional decisions by following a predefined investment strategy.
Cons
- Investment choices may be limited compared with full-service brokerages.
- Fees can reduce returns, especially for smaller or less frequent deposits.
- Automated strategies may not suit changing personal financial goals.
- Market losses remain possible, even when investing is fully automated.
- Account setup may require sensitive identity and financial information.
FAQs for Autopilot - Investment App
What is Autopilot - Investment App and how does it work?
Autopilot - Investment App is designed to help users follow and manage investment strategies through a mobile interface. Depending on the available features and connected brokerage accounts, it may track portfolios, mirror selected investment activity, provide market information, and send notifications. Before using it, review exactly how trades are executed, which assets are supported, and whether the app acts as an educational tool, an automation service, or both.
Is Autopilot - Investment App safe to use with my brokerage account?
Safety depends on the permissions you grant, the brokerage connection method, and the security practices used by both services. Read the app’s privacy policy and terms carefully before linking an account, and confirm whether your login is handled through a secure brokerage authorization page or stored by the app. Never share passwords or verification codes outside official sign-in screens, and enable two-factor authentication whenever possible.
Can Autopilot automatically buy and sell investments for me?
Some features may support automated investing or copying of selected strategies, but the exact level of automation can vary by account type, brokerage, region, and subscription plan. Do not assume that following a portfolio means every transaction will be completed at the same price or time. Check whether trades require approval, how execution works, and how you can pause or cancel automated activity.
How much does Autopilot - Investment App cost?
The app may be free to download while offering paid subscriptions, premium tools, or other charges. In addition to any app fee, users should consider brokerage commissions, regulatory fees, fund expenses, spreads, and potential transaction costs. Pricing can change, so review the current information in the official app store listing and inside the app before starting a trial or entering payment details.
Is Autopilot - Investment App suitable for beginners, and can I lose money?
The app may be useful for beginners because it can present investment ideas, portfolio information, and automation tools in a simpler format. However, it does not eliminate investment risk or guarantee profits. Market values can fall, automated decisions may not match your goals, and past performance is not a reliable prediction of future results. Research every strategy, understand the risks, and invest only money you can afford to lose.

Autopilot - Investment App
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@joinautopilot.com, visit https://www.joinautopilot.com, or review their https://www.joinautopilot.com/privacy-policy.










